Iowa Legislature’s Steel Mill Incentive Is More Than a Tax Break
Iowa’s proposed steel mill incentives involve more than simply allowing Mesabi Metallics to pay less in taxes. Because the investment tax credits can be refundable or transferable, they can have financial value even when Mesabi does not owe enough Iowa taxes to use them itself.
The terms “Tax credit,” “refundable” and “transferable” sound complicated. What they mean is much simpler. Iowa could collect less money, pay money back, or allow someone else to use the tax benefit.
Iowa lawmakers have opened the door to about $1.36 billion in potential state incentives for the proposed Mesabi Metallics steel complex. But what does that actually mean for taxpayers?
Three words in the legislation help answer that question. Tax credit, refundable and transferable. Forget the accounting language for a moment. Here is what they mean in dollars.
A tax credit means Iowa collects less
Start with a simple example. Suppose a company owes Iowa $100 million in taxes and has a $100 million tax credit. Without the credit, Iowa collects $100 million but with the credit, Iowa collects nothing.
The state didn’t write a $100 million check. But it still has $100 million less to spend than it otherwise would have had.
The new law allows one qualifying rural project to receive an investment tax credit worth up to 10% of its qualifying investment. The Legislative Services Agency estimates the Mesabi project could generate more than $1.1 billion in investment tax credits alone.
“Refundable” means something more
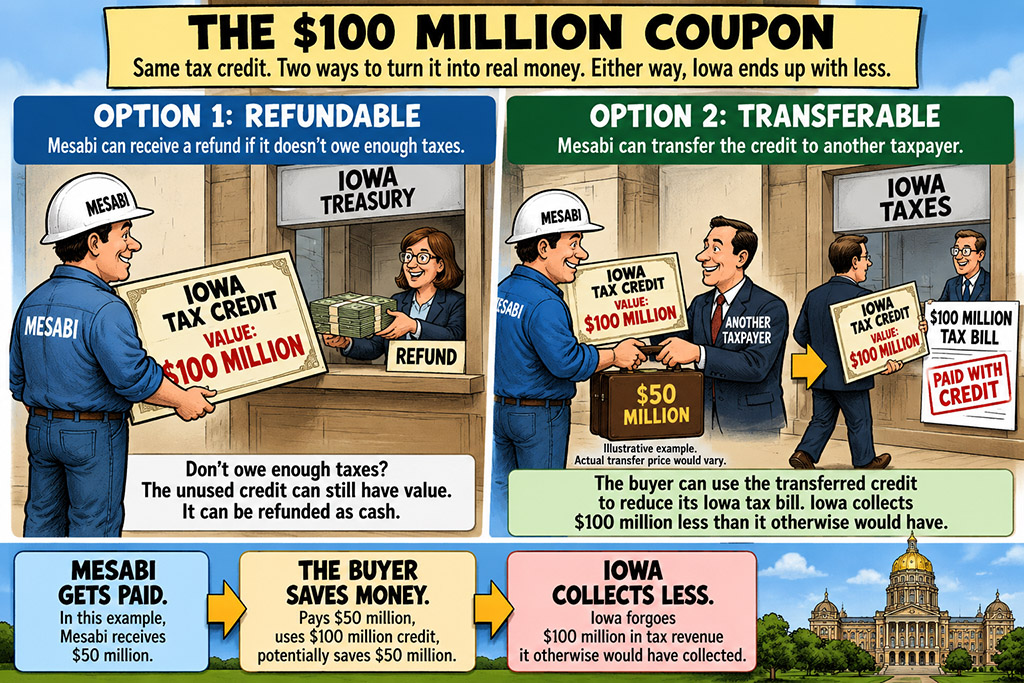
Now suppose Mesabi has a $100 million credit but owes Iowa only $20 million in taxes. It uses $20 million to eliminate its tax bill. What happens to the other $80 million?
Because the credit is refundable, Mesabi can potentially receive the unused amount as an $80 million refund payment from Iowa taxpayers rather than simply losing it. The company could also elect to carry the unused credit forward.
That distinction matters, because a refundable tax credit can be worth money even when the company doesn’t owe enough taxes to use it. In fact, Iowa’s Legislative Services Agency assumes in its fiscal analysis that these investment credits will be fully refunded rather than saved to offset future taxes.
LSA has explained the concept even more plainly in its general analysis of Iowa tax credits, that refundable credits can benefit taxpayers even when they have no income-tax liability, are “directly comparable to appropriations,” and typically are redeemed at 100% of their awarded value.
In other words, calling this simply a “tax break” does not tell the whole story.
“Transferable” means someone else can use the credit
Mesabi does not necessarily have to use the tax credit itself. With approval from the Iowa Economic Development Authority, it can transfer the credit to another qualifying taxpayer – an individual or a company.
Here is a simplified example. Suppose Mesabi has a $100 million tax credit it doesn’t need. Another company expects to owe Iowa $100 million in qualifying taxes.
Mesabi could theoretically sell that $100 million credit to the company for, say, $50 million. The result would be that Mesabi gets $50 million for an otherwise unused credit. The buyer pays $50 million and could use the $100 million credit to eliminate $100 million in qualifying Iowa taxes for a potential $50 million benefit.
As a result, Iowa collects $100 million less than it otherwise would have.
The $50 million sale price is only an example; the law does not set that price. Transfers also require IEDA approval and must meet the law’s requirements. But the example shows why “transferable” matters. The credit isn’t valuable only if Mesabi has enough Iowa taxes to use it. It can become an asset that Mesabi can potentially turn into money by transferring it to another taxpayer that can use it.
And the law provides another benefit to Mesabi. The money it receives for transferring the credit isn’t treated as Iowa taxable income under the specified state income-tax provisions. The credit doesn’t multiply; there is still only one $100 million credit. But its transfer can create value for both Mesabi and the buyer.
For Iowa taxpayers, the bottom line is simpler: Iowa still gives up $100 million in tax revenue.
What about that $575 million cost of the tax incentives?
The state’s fiscal analysis estimates that the legislation will reduce Iowa’s General Fund by about $575 million compared with the previous MEGA law. That doesn’t mean the entire incentive is only $575 million.
Before the change, the program allowed investment credits of up to 5% for each of two qualifying businesses. The new law allows Iowa instead to give one qualifying rural business a credit of up to 10%. The roughly $575 million represents the additional impact of changing the law, not the total value of Mesabi’s incentives.
Other MEGA benefits, including sales-and-use-tax refunds and withholding-tax credits, remain available as well. Local property-tax exemptions also may be available.
Where does the money come from?
There isn’t a special account labeled “Mesabi.” Ultimately, it comes down to Iowa’s finances. If a tax credit eliminates taxes, Iowa collects less money. If a refundable credit exceeds the company’s tax bill, Iowa can pay out the difference. If a credit is transferred, another taxpayer can use it to pay less to Iowa.
None of that means a particular dollar comes directly out of a school, Medicaid, public safety or another specific program. But it does mean Iowa has less revenue available than it otherwise would have had.
That is what Iowa taxpayers will be investing
Supporters argue that these incentives could help Iowa secure a $15 billion industrial project promising thousands of construction jobs, about 1,750 permanent jobs and substantial economic activity. Those potential benefits are part of the equation, along with Iowa’s contribution.
A tax credit can mean taxes Iowa doesn’t collect. A refundable credit can mean money paid out even when the recipient doesn’t owe enough taxes to use the credit. And a transferable credit can allow another person or company to use the tax benefit instead.
The terminology is complicated, but the effect isn’t. Iowa either collects less money or pays out more money than it otherwise would.
Whether the steel mill ultimately produces enough economic benefit to justify that investment is a separate question. But taxpayers should first understand what Iowa is putting on the table.
When Iowa lawmakers returned to Des Moines for a one-day special session Friday, the stated purpose was straightforward: change Iowa’s Major Economic Growth Attraction, or MEGA, program to help secure a proposed $15 billion Mesabi Metallics steel mill in Lee County.
House File 2801 passed the House 75-17 and the Senate 28-19. The legislation allows the Iowa Economic Development Authority to provide a qualifying rural project an investment tax credit of as much as 10% of its qualifying investment. The nonpartisan Legislative Services Agency estimates that change could provide roughly $1.15 billion in investment tax credits, with existing MEGA incentives potentially adding another $215 million.
But the percentage and the total dollar amount tell only part of the story.
A closer reading of HF 2801 shows lawmakers made several less obvious changes to how Iowa can award those incentives. Changes that involve when the money can begin flowing, whether the recipient actually needs the tax liability to use the credits, what kind of site qualifies, and how much of the MEGA program can be directed toward a single company.
Those provisions received considerably less public attention.
Iowa doesn’t have to wait for the entire project
Perhaps the most important change involves when Mesabi could begin qualifying for incentives.
Under the legislation, IEDA does not have to wait until the entire proposed steel complex is operating. A tax-credit certificate can be issued after the project or a “designated portion” of the project has been placed in service, provided at least 50% of the jobs associated with that project or designated portion have been added to payroll and meet the wage requirement.
The LSA’s fiscal analysis doesn’t treat that language as merely theoretical. Its calculations specifically assume that investment tax credits will be issued as portions of the project become operational. The agency projects the facility at 8.7% capacity in fiscal 2029, 33.9% in 2030, 81.7% in 2031 and 100% in 2032.
That creates an important distinction for taxpayers. The proposed development is routinely described as a $15 billion project. But the law does not appear to require Iowa to wait for completion of that entire $15 billion project before tax benefits begin.
That raises questions that must be answered in the eventual IEDA agreement. What constitutes a “designated portion”? How large must it be? What happens if several portions are completed and receive credits, but later phases are delayed, reduced or never constructed?
The legislation includes repayment and clawback provisions, but the details of the eventual development agreement will matter.
A tax credit that can become cash
There is another easily overlooked provision. The new rural-project investment tax credits are both refundable and transferable.
Those words matter. A traditional nonrefundable tax credit generally reduces taxes a company otherwise owes. But HF 2801 allows the qualifying rural credit to be refunded, and it also allows the certificate to be transferred to another person or entity with IEDA approval.
In fact, the LSA’s fiscal analysis assumes the investment tax credits will ultimately be fully refunded rather than carried forward against future tax liability. In practical terms, that means the value of the incentive does not depend on Mesabi itself owing more than $1 billion in Iowa taxes.
Transferability drew questions during legislative consideration. IEDA Director Debi Durham said the state would retain approval authority over transfers and disputed suggestions that transferability would leave Iowa unable to recover improperly obtained incentives. HF 2801 also establishes liability and repayment provisions involving improperly obtained credits and certain transferees.
So transferability is not the same as an unrestricted ability to sell credits to anyone. But it does make the incentive considerably more usable, and potentially more valuable, than the phrase “tax credit” may suggest to an ordinary taxpayer.
The site doesn’t have to be certified
HF 2801 also changes a less glamorous but potentially significant requirement involving where a MEGA project can be built. For the new 10% rural credit, a project can satisfy the site requirement by being on property in which the business has a controlling interest, on a certified site larger than 250 acres, or by documenting to IEDA that it completed a site evaluation “commensurate with a certified site.”
That third option is new. A project this large therefore does not necessarily have to use one of Iowa’s formally certified development sites. IEDA can instead determine that the company’s evaluation meets a comparable standard.
That may prove entirely reasonable for an industrial complex of unprecedented scale. But it is another example of the Legislature modifying an existing MEGA requirement to accommodate the circumstances of this particular project.
Two potential winners became one
The original MEGA structure permitted investment tax credits of up to 5% for as many as two eligible businesses. HF 2801 creates another option: up to 10% for one eligible business in a rural county. If IEDA awards that 10% credit, it cannot also make the two 5% awards.
Supporters describe that as combining the existing incentive capacity rather than increasing the overall program. Rep. Carter Nordman, the House floor manager, argued that Iowa was essentially combining two existing 5% incentives into one so the state could compete for a project far larger than lawmakers anticipated when MEGA was created.
Sen. Dan Dawson, a Republican who helped negotiate the original program, disagreed. He said the program was never intended to mean that “5% plus 5% equals 10%” for one company. Dawson ultimately voted against HF 2801.
That disagreement gets to the heart of the change. The overall amount of investment eligible for credits may remain within MEGA’s original aggregate structure, but Iowa has doubled the percentage of qualifying investment that can be awarded to a single business. And according to the LSA, no company received a MEGA incentive before lawmakers made that change.
A general law written for a specific project
HF 2801 never says “Mesabi Metallics.” It doesn’t need to.
The bill creates a 10% incentive for one qualifying business investing more than $1 billion in a county with 50,000 or fewer residents. But the LSA fiscal note explicitly says its analysis assumes the changes were made to allow a MEGA award for the proposed Mesabi Metallics steel manufacturing facility.
That distinction matters. The Legislature enacted a generally worded statute, but it did so in response to a specific project with requirements the existing program apparently did not accommodate.
There is nothing inherently unusual about writing legislation that way. But Iowans evaluating the deal should understand that lawmakers did considerably more Friday than simply authorize “an incentive for a steel mill.”
They changed how MEGA works.
All in one day
Those changes also received remarkably little time for legislative examination.
The House study bill went to a subcommittee at 9 a.m. Friday. It proceeded through subcommittee and Ways and Means, became HF 2801, received a fiscal note and passed the House. The Senate then passed it that evening. The entire legislative process occurred October 2.
And the fiscal note produced that same day estimated that HF 2801’s change to the investment credit alone would reduce General Fund revenue by an additional $575 million compared with what Mesabi could have received under existing law.
Supporters argued that speed was necessary to compete for an unusually large economic-development opportunity. They also emphasized that Iowa won’t simply write Mesabi a check upfront: portions of the project must enter service, employment requirements must be satisfied, credits are distributed over ten years, and the program includes repayment and clawback provisions.
Those are significant taxpayer protections, but they don’t eliminate the larger question raised by Friday’s session. Iowa lawmakers were asked to alter one of the state’s largest economic-development programs for what state officials describe as the largest economic-development project in Iowa history. In a matter of hours, they approved changes governing who can receive the incentive, how much one company can receive, when it can begin receiving it, how the credits can be converted into value, and what kind of site can qualify.
The $1.4 billion headline is important. The fine print is just as important.
At a Glance
How the Steel Mill Tax Credits Work
What is a tax credit?
It reduces taxes that otherwise would be paid. A $100 million credit used against a $100 million tax bill means Iowa collects $100 million less.
What does “refundable” mean?
If Mesabi earns more in credits than it owes in taxes, the unused credit can potentially be paid back as a refund rather than simply going unused.
What does “transferable” mean?
Mesabi can, with state approval, transfer the credit to another taxpayer, an individual or a company, that can use it against qualifying Iowa taxes.
Could someone buy a tax credit for less than it is worth?
Potentially. For example, someone could theoretically pay Mesabi $50 million for a $100 million credit and use that credit against $100 million in qualifying Iowa taxes. The actual price would be negotiated, and the transfer would require IEDA approval.
Who benefits in that example?
Mesabi turns the credit into $50 million. The buyer potentially saves $50 million. Iowa collects $100 million less in taxes.
Does the credit double when it is transferred?
No. There is still only one $100 million credit. It simply moves from Mesabi to another taxpayer.
Why does refundability matter so much?
Mesabi doesn’t necessarily need a large Iowa tax bill, or even another taxpayer willing to buy the credit, to receive its value.
What’s the bottom line?
Whether credits are used, refunded or transferred, Iowa ultimately collects less revenue or pays out more than it otherwise would.
Iowa Farmers Sue USDA Over Canceled Solar Funding
Lawsuit Alleges that USDA Violated Federal Law by Applying New Restrictions to Projects Iowa farmers invested in solar projects expecting federal assistance. Then USDA changed the rules. Now they want a court to make the government honor its commitments.Iowa...
Fool Us Once, Mr. President, Shame On You
Fool Us 13 Times, Shame on UsThere’s an old saying: Fool me once, shame on you. Fool me twice, shame on me. Add 11 more times Iowans were fooled by Donald Trump, and you have the latest Trump promise of the world's biggest steel mill that many feel is nothing more...
Before Iowa Bets On a Steel Mill, First Think About Foxconn
The Proposed Iowa Steel Mill: Lessons from Wisconsin’s Foxconn FailureWisconsin's failed $10 billion manufacturing promise offers lessons as Iowa considers incentives for a proposed $15 billion steel mill.A Wisconsin reader's letter to the Des Moines Register this...
The $1.5 Billion Question: Why the Rush to Subsidize?
Reynolds’ Timing to Dedicate Taxpayer Funds for the Mesabi Steel Mill Is QuestionedTrump's commerce secretary says the deal is done. So why are Iowa lawmakers being called back to offer hundreds of millions more in tax incentives?Iowa's proposed $15 billion steel mill...
The Hook: How Trump Benefits from False Claims
The Trump Tactic for Avoiding Questions about His Big LiesThe $15 billion Iowa steel mill may become everything Trump says it will. But his announcement illustrates a political technique Iowans have seen before: make the promise enormous, collect the political benefit...
Trump Announces $15 Billion Steel Mill for Southeast Iowa
Suspicions raised due to lack of details, timing of announcementThe massive project could bring thousands of jobs and make Iowa a major U.S. steel producer. But production isn't expected until 2030, and important questions about financing, incentives, environmental...
Iowa Legislators at Odds Over the Iran War
Hinson Calls for End to Iran War as Grassley and Ernst Vote to Continue ItIowa Republican Rep. Ashley Hinson is now calling for an “immediate end” to the nearly seven-month Iran war, even as Iowa Republican Sens. Chuck Grassley and Joni Ernst voted Thursday against a...